Understanding Fence Financing No Credit MA Options and How They Work
Massachusetts homeowners can finance a fence with zero credit impact by starting with soft-pull point-of-sale pre-qualification platforms, which return estimated rates in under 60 seconds without touching your credit score, and by qualifying through alternative income and banking verification if you have no credit or a low score. These platforms are available through contractor quoting portals for residential properties in Massachusetts, and they let you compare unsecured installment loans from $1,000 to $25,000 or more with terms from 3 to 60 months before any hard credit pull. Once you accept an offer, lenders may verify 3 to 6 months of bank statements, steady paystubs, and a debt-to-income ratio up to 45% or 50% instead of relying on a traditional FICO threshold. This approach keeps your credit file untouched during rate shopping and gives homeowners across the Bay State a practical path to secure a perimeter, dog run, or garden enclosure without immediate rejection.
When homeowners across the Bay State search for ways to secure their perimeter, navigating the financial landscape can feel overwhelming—especially when worried about credit scores. Whether you live in MetroWest, the North Shore, or Western Massachusetts, managing home improvements requires an approach that balances property needs with long-term financial health. For many residents, fence financing no credit MA is a realistic option because modern lending models have evolved beyond rigid, traditional credit score thresholds.
In traditional home improvement lending, banks evaluate your three-digit FICO score to measure risk. If you have a thin credit file or a score below standard benchmarks, conventional banks might turn you down. However, alternative lending structures assess creditworthiness through different metrics, allowing homeowners to finance essential containment barriers, dog runs, or deer fencing without facing immediate rejection.
Soft Credit Inquiries vs Hard Credit Pulls for Fence Loans
The most important distinction to understand when shopping for financing is the difference between a soft credit inquiry and a hard credit pull.
A soft credit inquiry acts as an initial snapshot of your financial profile. Lenders use soft pulls for pre-qualification, allowing you to view estimated loan amounts, interest rates, and repayment terms without leaving a footprint on your credit file. You can check multiple options across different platforms without dropping your score by a single point.
A hard credit pull, by contrast, occurs when you formally accept a loan offer and complete the final borrowing agreement. A hard pull is recorded on your credit report with major bureaus (Equifax, Experian, and TransUnion) and can temporarily lower your credit score by a few points for up to twelve months.
| Feature / Metric | Soft Credit Inquiry (Pre-Qualification) | Hard Credit Pull (Formal Loan Approval) |
|---|---|---|
| Credit Score Impact | Zero (Score remains unchanged) | Small, temporary dip (typically 2–5 points) |
| Visible to Other Lenders? | No (Only visible on your personal reports) | Yes (Recorded on official credit files) |
| Purpose | Rate comparison and initial eligibility | Final loan contract execution |
| Required Information | Basic contact info, income, estimated credit | Full SSN, formal ID, detailed financial data |
| Commitment Level | Non-binding, no obligation to borrow | Legally binding borrowing agreement |
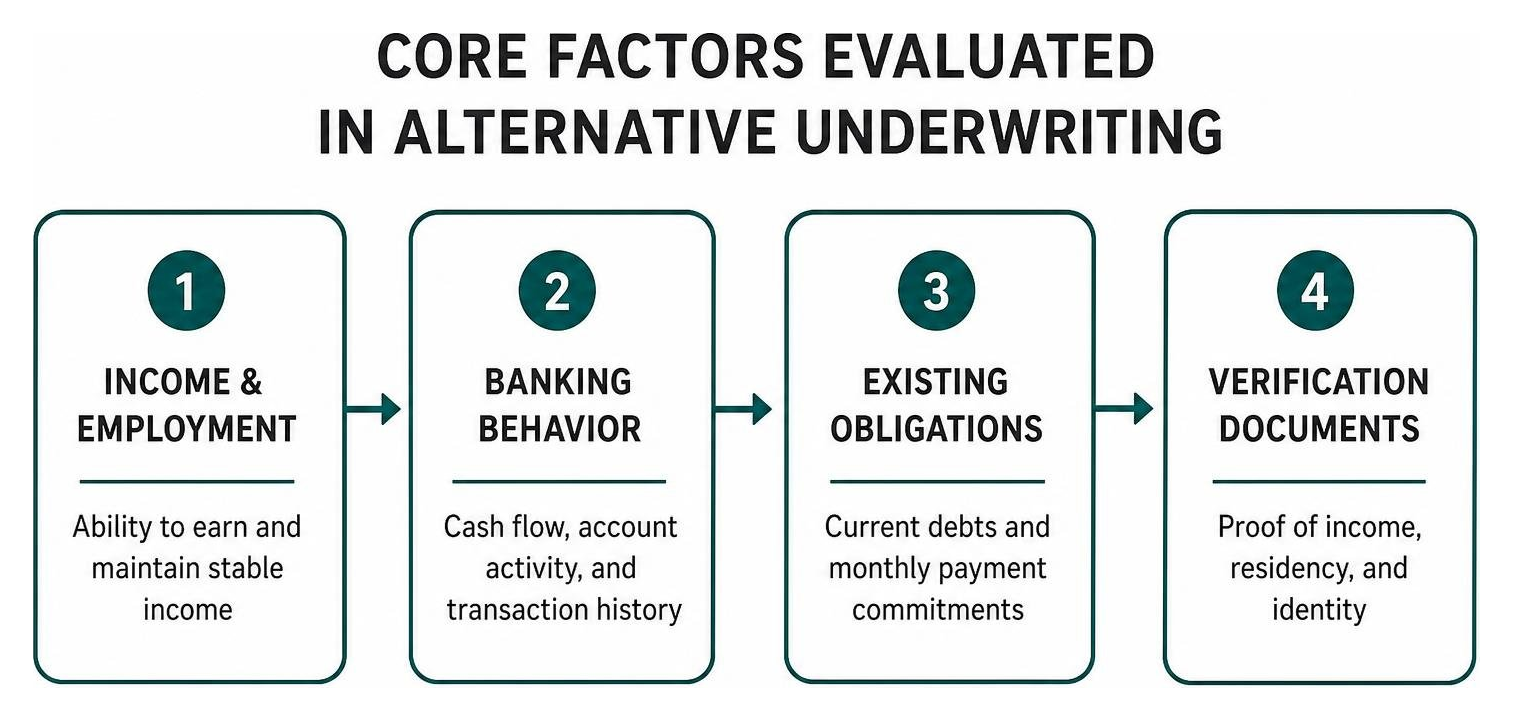
Alternative Underwriting: Income, Employment, and Banking History
If you have no credit history or a damaged credit profile, alternative underwriting pathways look at real-time financial stability rather than past credit mistakes. Lenders participating in these programs frequently focus on:
- Proof of Steady Income: W-2 statements, recent paystubs, or 1099 tax forms demonstrating consistent earnings.
- Bank Statement Verification: Reviewing 3 to 6 months of active checking account history to verify positive cash flow and the absence of non-sufficient fund (NSF) penalties.
- Debt-to-Income (DTI) Limits: Evaluating your monthly debt obligations against your gross monthly income, with many specialty lenders accepting DTI ratios up to 45% or 50%.
- Employment Stability: Verifying at least six to twelve months of continuous employment with your current employer.
By proving your current ability to manage recurring monthly payments, alternative underwriting opens the door to project approval without requiring an established credit history.
Top Funding Pathways for Massachusetts Homeowners with Low or No Credit
Finding the right financing vehicle depends on your budget, property size, and how fast you need the installation completed. Several accessible options exist for Bay State homeowners looking for affordable installment structures.

Exploring Point-of-Sale Platforms for Fence Financing No Credit MA
Point-of-sale (POS) fintech lending platforms have transformed exterior home improvement funding. When exploring solutions for containment solutions like a dog fence, homeowners can take advantage of digital portals embedded directly into the contractor's quoting process.
These platforms feature rapid pre-qualification engines that return offers in under 60 seconds. Rather than waiting days for a bank branch appointment, you can review unsecured personal installment loans ranging from $1,000 to $25,000 or more, with terms extending anywhere from 3 to 60 months.
Many point-of-sale networks connect with multiple lending partners simultaneously, matching you with institutions that approve credit scores starting as low as 550 or evaluate applications using alternative employment metrics.
Personal Home Improvement Loans and Government Assistance Programs
Beyond point-of-sale portals, other accessible funding options include:
- Fixed-Rate Personal Loans: Unsecured personal home improvement loans provide a lump sum upfront with fixed monthly payments. Because these are unsecured, they require no home equity, no property appraisal, and zero collateral.
- Secured Personal Loans & Co-Signers: If your individual credit profile cannot secure a competitive APR, adding a creditworthy co-signer or placing collateral (such as a vehicle title or certificate of deposit) can dramatically lower interest rates.
- USDA Section 504 Home Repair Program: For low-income homeowners in designated rural Massachusetts areas, the USDA offers Section 504 grants of up to $7,500 and low-interest loans up to $20,000 (or combined packages up to $27,500 at a fixed 1% interest rate) to repair safety hazards, which can include installing protective garden fence systems.
- Local Community Development Programs: Certain Massachusetts municipalities offer residential micro-loans or deferred-payment assistance for exterior barrier upgrades that resolve code compliance or zoning safety requirements.
Comparing Costs, Terms, and Hidden Risks in Massachusetts Fence Financing
Understanding the total cost of ownership is vital before signing any financing agreement. While monthly installments make upfront expenses manageable, total interest and processing fees can add up if not monitored closely.
Typical Interest Rates, Payment Terms, and Loan Caps in 2026
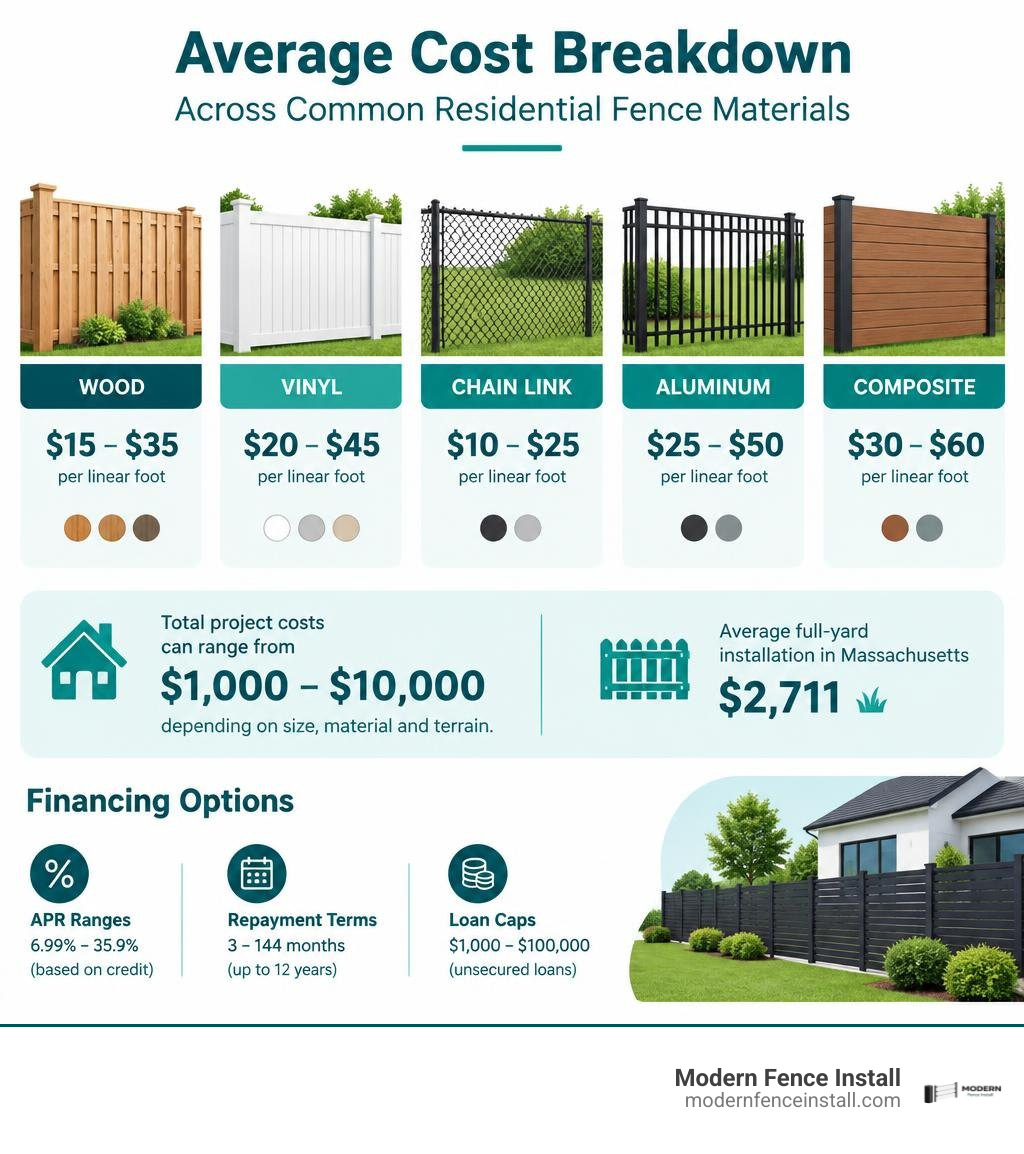
The average residential fence installation across Massachusetts ranges between $1,580 and $3,418, with standard full-yard installations averaging approximately $2,711. Depending on your linear footage and property terrain, total project costs can vary from $1,000 for small garden enclosures to upwards of $10,000 for large boundaries.
Lenders offering unsecured home improvement financing structure their terms around your credit profile and verified income:
- Annual Percentage Rate (APR): Fixed APRs typically start at 6.99% to 7.99% for excellent credit, range from 12% to 20% for fair credit, and span 20% to 35.9% for low- or alternative-credit borrowers.
- Repayment Terms: Options range from short-term 3- to 12-month installment schedules up to extended 84- or 144-month (12-year) terms.
- Loan Caps: Personal unsecured loans for home improvement range from $1,000 up to $100,000, easily covering full perimeter enclosures and specialized low-profile mesh installations.
Protecting Yourself from Predatory Terms in Fence Financing No Credit MA
When credit scores are low, predatory lenders often introduce misleading financing structures. Stay vigilant and review every contract line item:
- Deferred Interest Traps: Some promotional offers advertise "0% Interest for 12 Months." However, if a single dollar remains unpaid when the promotional period ends, the lender may retroactively charge the full APR (often 29.99% or higher) across the entire original loan balance.
- Prepayment Penalties: Always verify that your loan agreement allows early payoff without extra fees or penalties, letting you eliminate interest charges as soon as your cash flow allows.
- Compounding Interest Structures: Ensure your loan uses simple, fixed-rate interest rather than daily compounding rates that inflate your overall balance.
- Hidden Processing Fees: Check for origination fees (which can range from 1% to 8% of the loan value) subtracted directly from the disbursed funds.
To better understand standard contract terms and avoid financing traps, review our collection of educational homeowner guides and resources before moving forward with your project.
How to Qualify and Apply for Backyard Fencing Without Hurting Your Score
Applying for exterior project financing without damaging your credit score requires a step-by-step approach. By gathering documents early and using digital pre-qualification tools, you can move from an initial estimate to project installation seamlessly.
Step-by-Step Approval and Rapid Funding Timeline
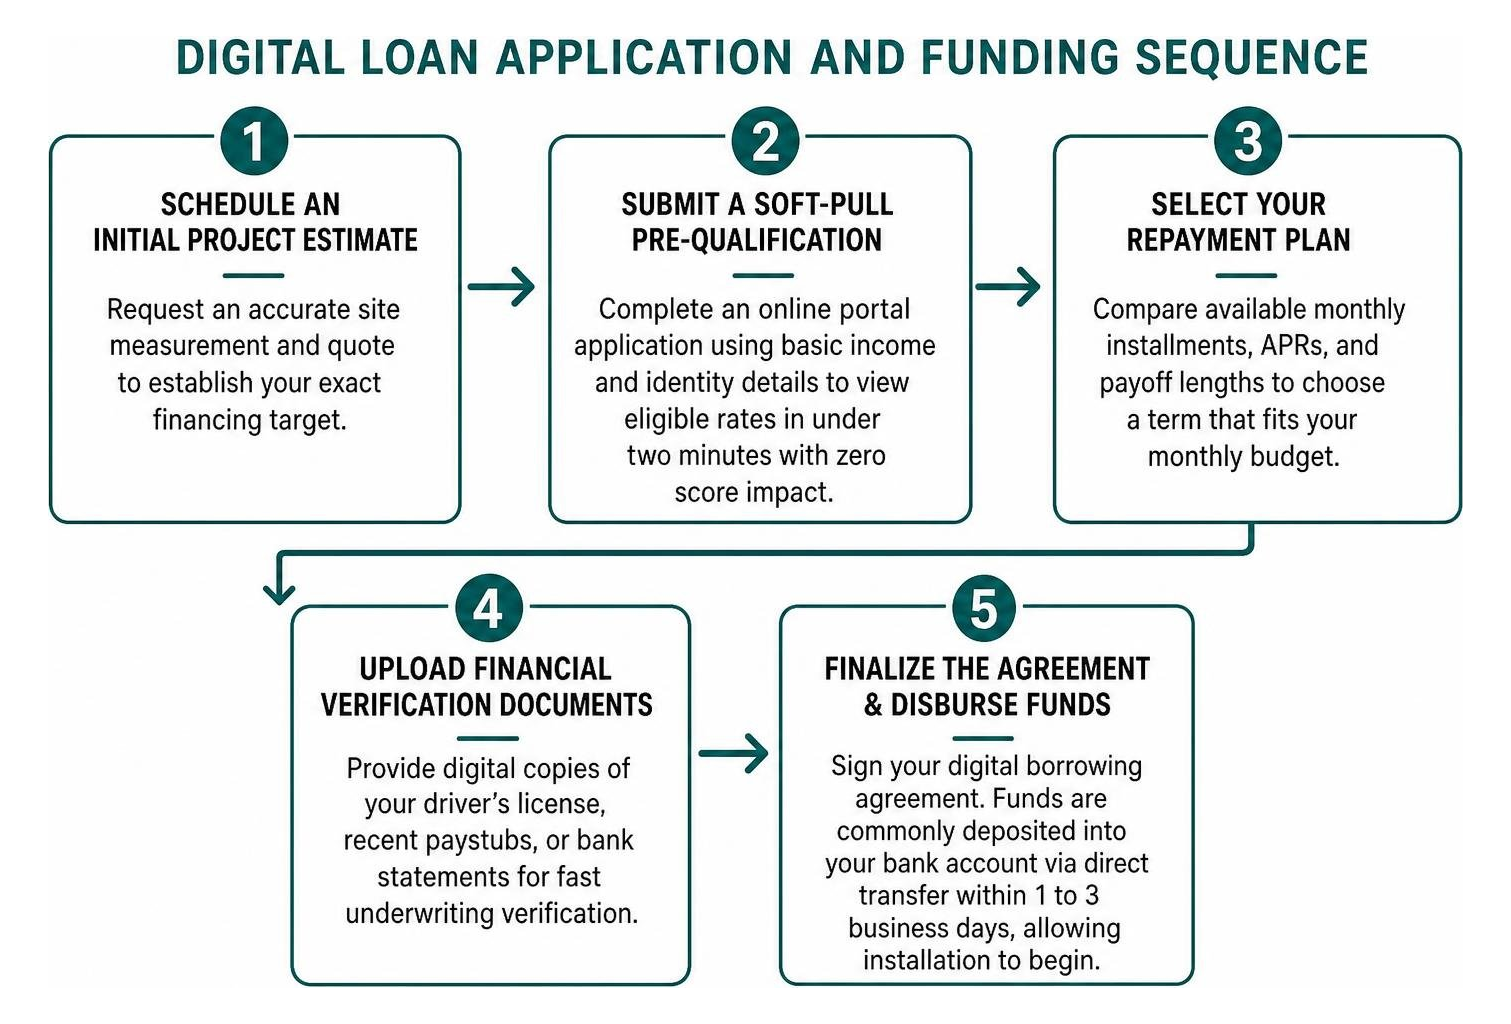
- Schedule an Initial Project Estimate: Request an accurate site measurement and quote to establish your exact financing target.
- Submit a Soft-Pull Pre-Qualification: Complete an online portal application using basic income and identity details to view eligible rates in under two minutes with zero score impact.
- Select Your Repayment Plan: Compare available monthly installments, APRs, and payoff lengths to choose a term that fits your monthly budget.
- Upload Financial Verification Documents: Provide digital copies of your driver's license, recent paystubs, or bank statements for fast underwriting verification.
- Finalize the Agreement & Disburse Funds: Sign your digital borrowing agreement. Funds are commonly deposited into your bank account via direct transfer within 1 to 3 business days, allowing installation to begin.
Smart Material Selection to Lower Upfront Financing Needs
The most effective way to keep your loan amount and interest charges manageable is to choose cost-effective, durable fencing materials.
At Modern Fence Install, we specialize in engineered, non-electric steel-cable and low-profile mesh containment systems designed specifically for dogs, deer, and garden protection. Our purpose-built, low-visibility fences install without extensive digging or high material costs. By choosing engineered steel-cable mesh systems, Massachusetts homeowners save 30%+ compared to traditional solid fencing while achieving dependable containment and rapid 30-day turnaround times. Lower total project costs mean smaller loan balances, lower monthly payments, and less interest paid over time.
Frequently Asked Questions About Massachusetts Fence Loans
Can I get fence financing in MA if I have zero established credit history?
Yes. If you have a thin credit file or no established credit score, specialty lenders and alternative point-of-sale platforms evaluate applications using verified employment, recurring income, and positive banking cash flow. Supplying 3 to 6 months of active bank statements and proof of steady earnings can qualify you for installment funding without an existing FICO history.
How fast can loan funds be deposited into my account for fence installation?
Once you review your pre-qualified terms and complete final document verification, most digital lending partners disburse funds via electronic direct deposit within 1 to 3 business days. Some platforms even provide direct-to-contractor funding within 24 to 48 hours, allowing your installation schedule to proceed without delay.
Will checking my loan rates through contractor portals lower my credit score?
No. Initial rate checks and pre-qualification inquiries conducted through digital home improvement financing portals utilize soft credit pulls. A soft pull allows you to view estimated APRs, loan caps, and monthly payments without impacting your credit score or appearing on your public credit file.
Protect Your Yard with Stress-Free, Affordable Containment
Installing a durable perimeter barrier around your Massachusetts home should not drain your emergency savings or compromise your credit profile. With modern soft-pull pre-qualification tools, alternative underwriting methods, and transparent fixed-rate installment plans, you can secure your property while protecting your financial peace of mind.
At Modern Fence Install, we design and install high-strength, non-electric steel-cable and low-profile mesh fences that blend seamlessly into your natural landscape. Our systems keep dogs safe, deter deer, and protect gardens without requiring heavy excavation—all while saving you 30%+ compared to traditional solid fences with installation completed in under 30 days.
Ready to explore transparent, budget-friendly payment options for your backyard? Visit our flexible fence financing page today to check your options with zero credit impact and start planning your installation.